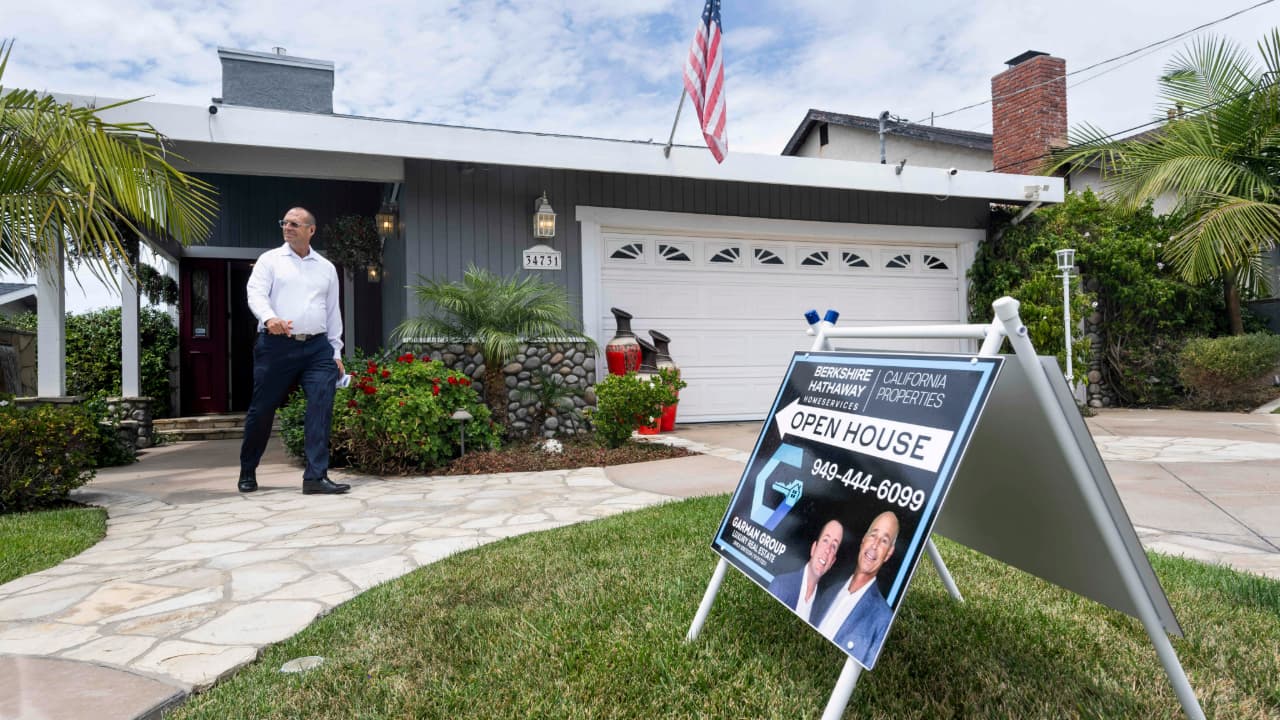
Americans who are looking to buy a home are facing a difficult market in terms of affordability due to high mortgage rates that are expected to persist into next year.
Interest rates on a 30-year fixed mortgage have risen more than a full percentage point since the start of the year, with data from Freddie Mac showing a rise from 6.16% on Jan. 8 to 7.24% as of Oct. 29.
The latest data shows a modest decline in recent weeks after rates hit a recent peak of 7.4% in early October, which was the highest rate for the 30-year mortgage since the fall of 2023.
Mortgage Bankers Association chief economist Mike Fratantoni told FOX Business that the run-up in mortgage rates has "slowed activity quite a bit" in comparison with last year.
HOMEBUYERS GET AN ADVANTAGE IN DOZES OF US CITIES – BUT PAY A STEEP PRICE
Fratantoni noted that home purchase application volume is down about 15% from this time a year ago, while refinance applications fell even further because "at this level of rates there's just not a lot of incentive for folks to refinance their existing loans."
That recent trend has created a dynamic where current homeowners with lower interest rates on their mortgages are reluctant to sell their home and move, given a new mortgage would entail a higher interest rate.
"If you go back to where we were in the pandemic, we had record low mortgage rates — people were getting 30-year fixed mortgage rates below 3%," Fratantoni said. The surge in inflation caused mortgage rates to more than double in 2022, which created the lock-in dynamic that has reduced mobility as rates rose in recent years.
"Now with mortgage rates spiking again, that's just going to reinforce that effect," he said, adding that he expects the pace of home sales and home construction to slow over the next year relative to where the market would be at with lower rates as would-be buyers grapple with affordability concerns.
THE HOUSING MARKET COULD FINALLY BECOME AFFORDABLE AGAIN. HERE'S WHAT IT WOULD TAKE
Fratantoni said that the affordability of homeownership is determined by a "three-legged stool" that comprises mortgage rates, home prices and household incomes.
While mortgage rates have been elevated, home prices remain high relative to incomes but have moderated in some parts of the country, while wage growth is outpacing rents and home prices in much of the U.S.
"It's getting a little bit better, but this spike in mortgage rates is definitely the hurdle right now and affordability conditions remain challenging, particularly for a lot of first-time homebuyers," he noted.
MORTGAGE RATES SURGE TO HIGHEST LEVEL SINCE 2023 AS BOND YIELDS SPIKE
The Mortgage Bankers Association's outlook for mortgage rates reflects some relief from the current levels, though they're expected to remain above 7% in 2027, Fratantoni said.
"Our expectation is that this spike we've had is probably a little bit overdone, so we think rates are going to come down a bit but are still going to remain above where we would have forecast just a couple of months ago," he said. "Our current forecast has the 30-year fixed mortgage rate staying above 7% really throughout 2027."
"That really is going to be very sensitive to developments geopolitically — what's happening in the Middle East, impacts on oil prices, impacts on inflation; and developments with respect to the likely path for the Fed and also this ongoing pressure from very large federal deficits and the growing federal debt — that's putting upward pressure, particularly on longer term rates," Fratantoni said.